
Dubai off-plan payment plans are the main reason many buyers can afford a new apartment or villa in the city. You pay in stages instead of all at once. That sounds simple. But the schedule hides details that decide how safe, how expensive and how flexible your purchase really is.
A glossy brochure shows “60/40” or “post-handover” in big letters. The contract shows the real terms. This guide gives you five checks to run before you sign anything, so you understand your Dubai off-plan payment plans line by line.
It is general information, not legal or financial advice. Always have a licensed lawyer read the contract before you pay.
Table of Contents
- How Dubai Off-Plan Payment Plans Work
- Check 1: RERA Registration and the Escrow Account
- Check 2: The Payment Schedule Itself
- Check 3: The Total Cost Beyond the Price
- Check 4: Handover and Post-Handover Terms
- Check 5: Contract Clauses, Resale and the Developer
- Red Flags to Walk Away From
- Quick Checklist Before You Sign
- Frequently Asked Questions
How Dubai Off-Plan Payment Plans Work
Off-plan means you buy a property that is still being built, and Dubai off-plan payment plans spread the price over time. The developer sells units early and collects the price in instalments. Most Dubai off-plan payment plans follow the same basic pattern:
- Booking fee: a deposit that reserves the unit.
- Down payment: the first large payment, paid when you sign the sales agreement.
- Instalments: payments during construction, tied either to dates or to building milestones.
- Handover payment: the final part, due when the unit is ready.
- Post-handover instalments: on some projects, a part of the price is paid after you receive the keys.
Developers label Dubai off-plan payment plans with short splits such as 60/40 or 80/20. The first number is usually what you pay before handover. The second is what remains at or after handover. The exact split differs from one developer and project to the next, so never assume a label means the same thing everywhere.
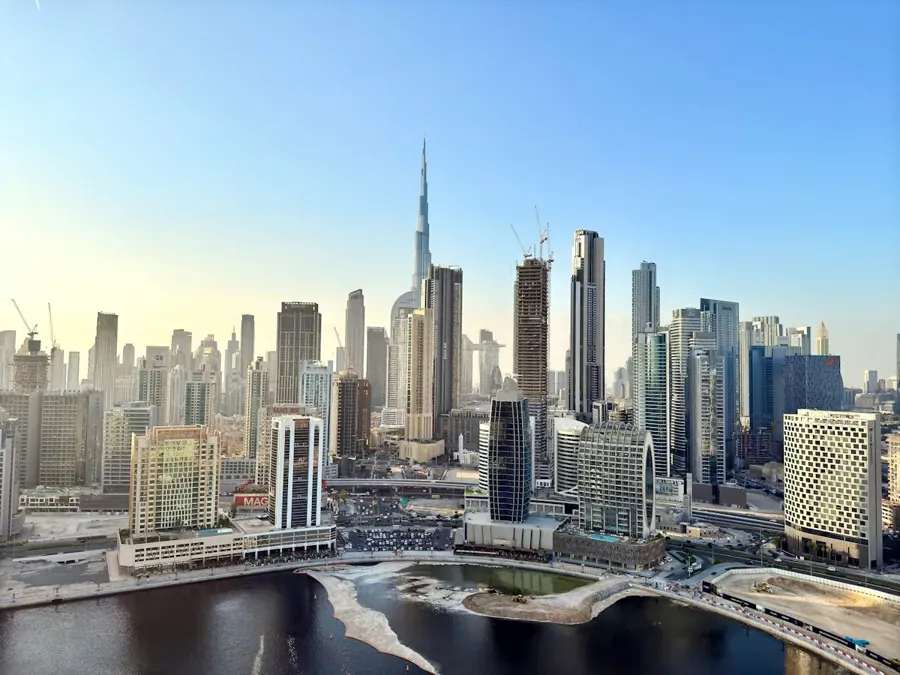
The market is active. You can see how strong demand has been in our report on Dubai’s off-plan market breaking records. Strong demand is exactly when buyers rush, and rushing is when mistakes happen. Slow down and run the five checks below.
If you are still deciding whether off-plan suits you, read why off-plan properties are taking over Dubai’s real estate market first. Then come back to the details of Dubai off-plan payment plans here.
Check 1: RERA Registration and the Escrow Account
This is the first and most important check. Before you compare any Dubai off-plan payment plans, confirm that the project is legal and your money is protected.
Is the project registered with RERA?
RERA is the Real Estate Regulatory Agency. It works under the Dubai Land Department (DLD). Off-plan projects must be registered, and developers must hold the proper licences. Ask for the project registration details before you discuss Dubai off-plan payment plans with any agent. Then check them yourself on the official DLD channels. Do not rely on a screenshot sent by an agent.
Where does your money go?
Under Dubai’s escrow law, a developer who sells off-plan must open a separate escrow account for the project. Buyers’ instalments go into that account, not into the developer’s general bank account. According to the DLD, the law exists to regulate off-plan sales and protect buyers. You can read the regulator’s own explanation on the Dubai Land Department FAQ page.
The escrow account matters because withdrawals are controlled. Funds are released as construction progresses, and the release depends on an official technical report. That protects you from a developer who spends your money and builds nothing.
What to do in practice
- Ask for the name of the escrow bank and the account details for the project, and ask how the escrow account links to your Dubai off-plan payment plans.
- Pay only into that escrow account. Never pay cash, and never pay to a personal or agent account.
- Keep every receipt and bank transfer confirmation.
- Confirm your sale is registered in the Oqood system. Oqood is the DLD registration of an off-plan sale, and it records your interest in the unit.
If a seller cannot or will not explain the escrow account, stop. The best-looking Dubai off-plan payment plans are worthless if the money is not protected.
Check 2: The Payment Schedule Itself
Once the project is verified, study the schedule. This is the heart of every set of Dubai off-plan payment plans, and small differences add up.
Date-linked or milestone-linked?
Some plans ask for payments on fixed dates. Others link each payment to a construction stage, such as completion of a floor or the structure. Milestone-linked plans keep your payments closer to real progress. Date-linked plans can ask you to pay even when the site is behind schedule. Ask which type your Dubai off-plan payment plans use, and ask what happens if the building falls behind.
How big is the down payment?
The down payment is often the heaviest early cost. Check whether it includes the booking fee. Check whether any government fees are due at the same time. Then confirm you can pay it without touching your emergency savings.
Build your own payment calendar
Do not rely on the brochure table. Create a simple calendar with every date and amount from your Dubai off-plan payment plans. Add the currency, because your income may be in a different currency from the dirham. A short calendar shows whether a plan is comfortable or whether three large payments land in the same quarter.
| Item to confirm | Question to ask |
|---|---|
| Down payment | How much, when, and is the booking fee included? |
| Instalments | Are they tied to dates or to construction milestones? |
| Handover payment | How much is due when the keys are ready? |
| Post-handover part | How many instalments, and is there any extra charge? |
| Late payment | What penalty applies if you pay late? |
Developers sometimes advertise Dubai off-plan payment plans with very low monthly figures. For an example of how a headline number looks, see our article on DAMAC’s installment plan starting from AED 1,999 per month. Read the full terms behind any headline figure. The monthly number alone never shows the total price or the total length of the plan.
Compare at least two or three Dubai off-plan payment plans for similar units. Look at the total price, not only the monthly amount. A lower instalment in Dubai off-plan payment plans can simply mean a longer plan or a higher final price.
Check 3: The Total Cost Beyond the Price
The unit price is not the full price. Many buyers compare Dubai off-plan payment plans by the sales price alone and are surprised later. Add the extra costs to your Dubai off-plan payment plans before you decide.
- DLD registration fee: a government charge paid when the sale is registered. It is commonly cited as 4% of the property price. Confirm the current figure with the DLD.
- Oqood or registration administration fees: smaller fixed charges linked to registering the sale.
- Agent commission: if you buy through a broker, ask who pays it and how much.
- Service charges: yearly fees for the building once it is complete. They affect your net return if you plan to rent.
- Mortgage costs: if you finance the final payment, add arrangement and valuation fees.
We explain each of these in detail in our guide to the hidden costs of buying property in Dubai. As a rule of thumb, set aside a clear buffer on top of the price. Developers sometimes offer to cover part of the registration fee as a promotion. If an offer includes this, get it in writing.
Also ask whether the plan has an administration fee for changing the schedule, for issuing a letter, or for transferring the unit. These small charges rarely appear in marketing material, yet they belong in the real cost of your Dubai off-plan payment plans.
Check 4: Handover and Post-Handover Terms
Two moments decide whether an off-plan purchase works: the handover and the time after it. Check both before you sign.
What is the handover date, and what if it slips?
Every contract states an expected handover date. Delays happen in construction everywhere. What matters is what the contract says about them. Look for the following:
- The exact handover date, and any grace period added to it.
- Whether you receive compensation or can cancel if the delay becomes long.
- How completion is certified, and who inspects the unit before you pay the final instalment.
Do not pay the handover payment until you have inspected the unit. List every defect in writing. This is called snagging, and good developers allow it. Ask how long the developer is responsible for fixing defects after handover.
How does a post-handover plan work?
Among Dubai off-plan payment plans, a post-handover plan lets you keep paying after you get the keys. For example, a part of the price is spread over a number of months or years after completion. Post-handover Dubai off-plan payment plans ease the cash needed at handover. It also moves your risk to a later period.
Ask these questions about any post-handover plan:
- Is the unit registered in your name while you still owe money, or only after the last payment?
- Can you rent the unit out during the post-handover period? Check whether the rent can cover the instalment.
- What happens if you miss a post-handover payment?
- Is the final price the same as under a shorter plan, or higher?
A post-handover option can be attractive for investors who plan to rent out the property. But it only works if the numbers hold. Estimate the rent honestly, subtract service charges, and compare it to the instalment. If the rent does not cover it, you carry the gap from your own pocket.
In short, the best Dubai off-plan payment plans give you clear dates, fair delay terms and a post-handover schedule you can afford even in a quiet rental market.
Check 5: Contract Clauses, Resale and the Developer
The last check covers the paperwork and the company behind it. Many problems with Dubai off-plan payment plans start with a clause the buyer never read.
Read the sales and purchase agreement
Do not sign on the spot, however attractive the Dubai off-plan payment plans look. Ask for the full agreement in advance and read it, or have a lawyer read it. Focus on these clauses:
- Default and cancellation: what you lose if you cannot continue paying. Dubai rules limit how much a developer may keep, depending on how far the project has progressed. Ask a lawyer for the current rule.
- Price and area: the final area can change slightly. Check how the price adjusts.
- Changes to the plans: whether the developer can change the layout, finishes or amenities.
- Dispute handling: where and how disputes are resolved.
Check the resale rules
Many investors plan to sell before handover. Ask early whether you can resell under your Dubai off-plan payment plans and under what conditions. Some developers require that you have paid a minimum share of the price first. Others charge a transfer fee or require a no-objection certificate. These rules directly affect your exit plan, and they differ between projects.
Check the developer’s record
Look at past projects and how their Dubai off-plan payment plans were handled. Were they delivered on time? Do the finished buildings look like the renders? Visit a completed project if you can. Read how the developer treated earlier buyers. Large, established developers are not automatically safe, and new developers are not automatically risky. The point is to judge evidence, not marketing.
If you prefer to work with a team that can walk through the contract with you, you can contact our team before you commit.
Red Flags to Walk Away From
Some warning signs should end the conversation. Walk away from Dubai off-plan payment plans if you see any of these:
- The seller will not name the escrow bank or the registered developer.
- You are asked to pay in cash or into a private account.
- Pressure to sign today because “the price ends tonight”.
- The payment plan in the brochure differs from the one in the contract.
- Promises of guaranteed returns without a written contract term.
- No clear handover date, or no written delay terms.
A genuine opportunity survives one more week of checking. A weak one does not. That is why verification matters more than speed in every set of Dubai off-plan payment plans.
Quick Checklist Before You Sign
- I confirmed the project registration and the escrow account details.
- I will pay only into the project escrow account and keep every receipt.
- I built a payment calendar for my Dubai off-plan payment plans and I can afford every date.
- I know whether payments follow dates or construction milestones.
- I added registration fees, commission and service charges to the budget.
- I understand the handover date, the delay terms and any post-handover instalments.
- I read the default, cancellation and resale clauses with a lawyer.
- I checked the developer’s earlier projects.
If you can tick all eight, you understand your Dubai off-plan payment plans better than most buyers. The official Know Your Rights guide from the Dubai Land Department is also worth reading. Remember that rules can be updated, so check the current version on the DLD website.
Frequently Asked Questions About Dubai Off-Plan Payment Plans
What are typical Dubai off-plan payment plans?
Most Dubai off-plan payment plans combine a booking fee, a down payment, instalments during construction and a final payment at handover. Some add post-handover instalments. Splits such as 60/40 or 80/20 are common labels, but every developer sets its own terms, so always read the contract.
Are Dubai off-plan payment plans safe for my money?
Dubai law requires off-plan developers to use a project escrow account, and withdrawals are controlled. This protects buyers when the rules are followed. Confirm the project is registered, pay only into the escrow account and keep receipts. No system removes every risk.
What is a post-handover payment plan?
It is a plan where part of the price is paid after you receive the keys, usually in monthly or quarterly instalments. It lowers the cash needed at handover. Check the final price, ownership registration and what happens if you miss a payment.
Can I sell before handover?
Often yes, but the developer’s rules apply. Some require a minimum percentage of the price to be paid first, and some charge a transfer fee or need a no-objection certificate. Ask for these conditions in writing before you buy, not when you want to sell.
What fees apply besides the price?
Expect a DLD registration fee, commonly cited as 4%, plus Oqood administration charges, any agent commission and later service charges. Mortgage fees apply if you finance. Check current figures with the DLD, and ask the developer which costs it covers.
What happens if the developer delays handover?
The contract decides. Look for a stated handover date, any grace period and the buyer’s remedies, such as compensation or cancellation. Dubai’s regulator also oversees developers. Ask a lawyer to explain the delay clause before signing, because wording differs between contracts.
Do I need a lawyer to buy off-plan in Dubai?
It is strongly advisable. A lawyer can check the sales agreement, the default and cancellation terms and the escrow details. The cost is small compared with the amount you commit across the whole plan, and it can prevent expensive misunderstandings.
Take the Next Step With Confidence
Good Dubai off-plan payment plans reward careful buyers. Verify the registration and escrow account, study the schedule, count every cost, understand handover and post-handover terms, and read the contract. If you would like help comparing projects or reading the terms, get in touch with the MR Real Estate team and we will guide you step by step.